Leaving an inheritance

Written by R. A, Stewart

“A good man leaves an inheritance for his children’s children.”-Proverbs 13:22

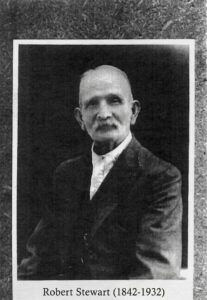
My great grandfather Robert Stewart started a brewery in 1905. This proved successful that by the time he died in 1932 just short of his ninetieth birthday he was a wealthy man in comparison to the average person. He also owned quite a bit of land when he died.

My grandfather Archie, Robert’s youngest son inherited the brewery and some land. Archie by the time he died in 1967 left land to my father, Doug some 250 acres. At some point he must have gifted him the land years prior to his passing. He also left my father cash when he died.

Going down another generation. 

My brother and I have possession of the land once owned by Granddad Archie. Talk about leaving an inheritance to your children’s children.

Robert, my great grandfather and Archie were good with their money in that they lived a modest lifestyle. Did not try to keep up with the Joneses and generally lived within their means.

The generations after the 1970s are ruled by greed and selfishness. The common use of credit cards is an example of this. 

The flashy advertising on TV taps into all of this by feeding into the narrative “You can have whatever you want and you can have it now.” 

It is the fear of missing out which the loan sharks are tapping into.

I have heard some bad money attitudes from people over the years and the most common is “You cannot take it all with you.”

This may be so but then why do these people go to work to earn money? People who spend all of the discretionary money with no thought for the future have no vision.

At some point in the future people will need money for medical expenses, dental expenses, new cars, retirement, and so on. The person with vision will set up their finances in such a way that they will have this money ready when the time comes.

“Men who have lots of money are selfish” is another one I have heard. If this is true then the men in our family who left large sums of money to their descendants must be selfish.

Only a gold digger would think like that and I will leave it at that.
“You have to spend your money on something.” is another comment I have heard. 

I am unaware of a law which says that you have to spend it. This kind of attitude will eventually lead to poverty at some point because there will come a time when your level of income will drop due to health or retirement. Making provision for your later years requires vision and maturity. It is the responsible thing to do.

Living within your means is a timeless principle. It was applicable to my great grandparents and it is still applicable today. The only difference is that in today’s society there is more pressure on people to part with their money and unless you learn to exercise self control and learn to discern then money will easily part ways with you. There is no magic formula, it is just a matter of applying the three basic rules of money management.

The three basics of personal finance are:

  1. Live within your means
  2. Save
  3. Invest

Once you have mastered the three rules then you will be better off than people who never look beyond the next pay day and just spend everything they make.

About this article

This article is of the opinion of the writer and is not financial advice. It may not be applicable to your personal circumstances, therefore discretion is advised. You may use this article as content for your website/blog or ebook.

Read my other articles on www.robertastewart.com
What should you do with an unexpected windfall

Written by R. A. Stewart

If you have suddenly come into a lot of money such as from an inheritance or a lottery win then the first thing you need to do is to get financial advice. This is certainly applicable to those who have no experience at investing. A financial advisor will also advise you of the taxation issues.

There are some basic rules to making the most of your windfall which I am going to share with you.

Rule number one: Know where you are going

If you have no clue as to what your plans are for the future then you are likely to fritter away your windfall with the result that you have nothing to show for it. I have seen it happen! Financial planning requires vision. Making provision for the future is the sensible and the responsible thing to do. It will make life easier knowing that you have the funds available when some unexpected bill crops up. 

A financial advisor needs to know what your intentions are with your windfall before they can help you. It is advisable to sit down with a pen and paper and write out your plans for the future. 

Rule number two: Get financially educated

Lack of financial literacy is the most common reason for poor financial outcomes. With so much information on personal finance available there is no excuse for financial ignorance. Books written by New Zealand financial advisors such as Frances Cook, Mary Holm, and Martin Hawes are worth reading. Your local library may have one of their books available.

Improving your financial literacy will enable you to make more informed choices when it comes to investing your money.

Rule number three: Know the risks

When there is an opportunity to make a capital gain there is also the chance that you may make a capital loss, but calculated risks must be taken with your money in order to put it to work. The key is to take risks which are compatible with your time frame. The longer your time frame the more risk you can take on. Having said that, it does not mean retired people should not invest aggressively in growth funds if they understand that a market meltdown will result in their portfolio taking a hit.

Rule number four: Take responsibility

It is up to you to take responsibility for your choices. This also means not blaming others when your investments are not performing up to expectations. It is also up to you to take responsibility for your own mistakes and learn from them. 

Rule number five: Don’t Leave your money in one place.

Diversify your investments according to your risk profile. This minimizes the chance of losing your money in one hit. This advice is more applicable in the internet age when millions of dollars are lost in banking scams. Don’t leave all of your money in an account which can be easily accessible online. It pays to have an account which is not connected to internet banking. This can be used for depositing large sums of money.

Rule number six: Invest your money

Inflation is the enemy of the conservative investor. Don’t just leave your money in an ordinary savings account; put it to work so that it is making you money. This does not necessarily mean you are taking unnecessary risks with your money. If you have a lot of money to invest there may be a temptation to invest in something offering interest rates at a much higher rate than the banks are offering. Do your due diligence with such offers. The higher interest rates on offer do not always reflect the higher risk which investors are accepting. This was the advice of some financial advisors prior to the Global Financial Crisis of the early 2000s. It fell on death ears as so many got their fingers burned with the collapse of several finance companies in New Zealand.

About this article

The contents of this article are of the opinion of the writer and may not be applicable to your personal circumstances therefore discretion is advised. You may use this article as content for your blog/website or ebook.

Check out my other articles on www.robertastewart.com

The cost of financial gifting

The cost of financial gifting

Written  by R. A. Stewart

Most parents want to help their children any way they can. It is the natural thing to do but there can be a high cost to this if your generosity is at the expense of your own needs and wants.

Here are some of the most common ways family’s make gifts.

House deposit

The New Zealand consumer magazine says that on average, parents gave $108,000 in 2022 to their children for house deposits. 62% of parents used their own savings. 

That money taken out of their own retirement savings will have a big impact on how much they will have when they retire. 

What parents need to consider is how much that money they are going to give to their children would be worth if they invested it in the markets. I am no mathematician but even so, know that this is an enormous amount of money that they are sacrificing. 

Some options need to be considered and one is guaranteeing the loan. If your son or daughter is able to take out the loan and parents guarantee the loan then this may be better. The parents still have their capital producing an income while at the same time their children are paying off the mortgage.

Early inheritance

It is good to leave an inheritance to your kids but not if they are just going to fritter it away and have nothing to show for it years later. After all, you were diligent enough to save and invest your money; if your kids have no interest in financial management then you are better off enjoying that money yourself or leaving it to a worthy cause. Another option is to have the money deposited into their kiwisaver so that they at least have the money when they reach the retirement age of 65. If your grown up children have learned to be responsible with their money then they will have their own kiwisaver account.

Getting your kids out of debt

Some parents will rescue their kids from debt time and again. It all depends on the circumstances of the debt. If your children have made a habit of getting into debt without learning how to manage without using credit then it is time for them to get budgeting advice. If it is you who have to make the sacrifices then it is time to put your foot down. 

Lending for businesses

Some folk approach mum and dad for loans to fund their business. If you lend money to your kids you are missing out on the capital gain that you would have had if that money was invested in the markets. It is also worth keeping in mind that most businesses fail within five years so that money could be gone in no time.

Lending for a wedding

The average cost of a wedding in New Zealand is around $30,000. It is a huge amount when you consider that most marriages don’t last the distance. If you stumped up the cash to pay for your child’s wedding, that $30,000 that you could have invested in your own retirement fund will mean that there will be a lot less money when you retire.

Educational loans

In New Zealand student loans are interest-free, so it just does not make sense to pay off your children’s educational loans when that same money could be invested and grown. Is it any wonder that student loan debts total over 2b in New Zealand. In 2021 there were over 14,000 kiwis who owed over $80,000. 

About this article

The information here is of the writer’s own opinion and may not be applicable to your personal circumstances, therefore, discretion is advised.

You may use this article as content for your website/blog or ebook.

Read my other articles on www.robertastewart.com
Financial Windfalls

Financial Windfalls

What it is

Written by R. A. Stewart

A windfall is a large amount of money you didn’t expect to receive. It could be $200, $1000, and more. It is an amount of money which was not budgeted for because it arrived unexpectedly. Unless you have mastered the art of financial discipline there is a risk that this good fortune will be frittered away with no improvement in your financial situation. It is important therefore that you have a plan for any unexpected cash that comes your way. In this article I will take a look at some of the more common forms of windfall and explain how best to take advantage of them.

Types of Windfalls

There are various types of windfalls, they could be:

An Inland Revenue refund

An inheritance of money or property

Lottery winnings

Gift from a rich relative

Life insurance payout

Employee bonus

These are just some of the kinds of unexpected windfalls one may receive during their lifetime. It is important not to pin all of your hopes of a financial miracle on a windfall if you are in some kind of financial mess. There is no substitute for diligence. Most of the windfalls are the result of living a responsible, diligent life; for example you are not going to receive a tax refund or an employee bonus if you are not working.

As for a lottery win; one must understand that for every one that gains a windfall in this way, there are many thousands who do not. It is a case of thousands contributing money into the pool but only a few taking out. This is luck! The amount of money lost by each individual lottery player is equal or in most cases greater than what one considers a large windfall.

How to take advantage of a windfalls

Gaining a windfall is one thing but taking advantage of it is another. People who come into a sum of money unexpectedly will follow the same pattern of behavior with any windfall as they do when they receive their pay packet…

Those who are spenders will spend it, those who are savers will save it, and those who are investors will invest it.

The end result will be that they will be in the same financial position as they were before  they received their windfall.

Is a Financial Windfall Discretionary Spending Money?

That all depends on your personal financial situation.

The answer is “No” if…

You have consumer debt.

You have credit card debt.

You have a student loan to pay back.

You have some other debt.

Even a mortgage.

The answer is “Yes” if…

You have absolutely no debt.

Money obtained from a financial windfall is discretionary spending money if you have no debt but that does not mean that you should just go and fritter it all away. Windfall money can be used to strengthen an already solid financial situation. One way you can do this is make voluntary deposits into your retirement fund or to put it toward your emergency fund.

About this article

This article is of the opinion of the writer and may not be applicable to your personal circumstances therefore, discretion is advised.

www.robertastewart.com