Diversify Diversify Diversify your investments

Diversify Diversify Diversify

Written by R. A. Stewart

“Put your money in several places-many places, in fact-because you never know what kind of bad luck you are going to have in this world.”-Ecclesiastes 11:2

The number one rule when investing your money is to diversify. That is to invest your money in several places. To invest money in one place is called “Placing all of your eggs in the one basket”. This is also known as speculating. 

During the 2007/08 Global Financial crisis there were people who lost their entire life savings when the company which they invested their money with went into receivership. The companies concerned were offering high interest rates to investors. 

There are sometimes stories floating around of people who made a fortune on the share market by investing in one company. That is all very well when it comes off, but such investors will try the same thing again and again and again and give up their gains plus a lot more.
Greed is what gets the better of some people. If you are going to speculate then do it with discretionary spending money. This is money you may have normally spent on entertainment, your hobbies, eating out, gambling, and the like.

Your retirement fund should not be used for one of your get rich quick schemes such as playing with the crypto market. That should be done separately.

Diversification is more than just spreading your portfolio among different companies, it is investing in different platforms. Investing your life savings in sharesies or robinhood is not diverse even if you were investing in a range of companies. You just don’t know what will happen to these platforms in the future.

The same thing applies when investing in crypto-currency. Don’t invest all of your bitcoin with one bitcoin exchange but spread it around among several to reduce your risk. But remember, Bitcoin is volatile so only play the crypto market with discretionary spending money.

Invest in different types of industries such as power companies, banks, insurance companies, farming, etc. 

In order to grow your wealth it is necessary to take calculated risks, not reckless ones. Share market investors have the option of investing in individual companies or managed funds which are a form of diversified investment. In this age it is possible for investors to deposit money into an online share market platform and purchase shares into individual companies for a minimum amount. This enables the ordinary man or woman in the street to get involved in the markets.

Hands-on investing will not only help you to grow your wealth but it also increases your financial literacy. With plenty of experience behind you there will be fewer mistakes as a result of better decision making.

Always remember that whenever there is a chance of a capital gain there is a chance for a capital loss. Your retirement fund balance may be down as it will be from time to time due to the volatility of the share market but that does not mean that you have lost money. It is the nature of the ups and downs of the markets, Get used to it!
You don’t have to be rich to invest but you have to invest to get rich so what are you waiting for?

About this article

This article is not financial advice and may not be applicable to your personal circumstances therefore discretion is advised. You may use this article as content for your blog or ebook.

Read my other articles on www.robertastewart.com

Tired of seeing your bank charge you $5-10 every time you withdraw cash abroad PLUS that hidden foreign transaction fee? 🤯 That’s money that should be buying you a gelato, a beer, or a souvenir. Wise gets you the real mid-market exchange rate with only tiny, transparent conversion fees from 0.42%. Stop funding your bank’s next vacation. Fund yours. 👉 Link in bio to get your Wise card! 

JOIN WISE HERE

#TravelHacks #WiseCard #NoHiddenFees
Leaving an inheritance

Written by R. A, Stewart

“A good man leaves an inheritance for his children’s children.”-Proverbs 13:22

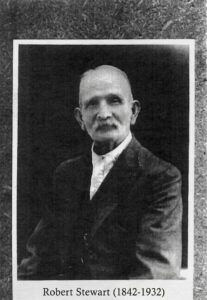
My great grandfather Robert Stewart started a brewery in 1905. This proved successful that by the time he died in 1932 just short of his ninetieth birthday he was a wealthy man in comparison to the average person. He also owned quite a bit of land when he died.

My grandfather Archie, Robert’s youngest son inherited the brewery and some land. Archie by the time he died in 1967 left land to my father, Doug some 250 acres. At some point he must have gifted him the land years prior to his passing. He also left my father cash when he died.

Going down another generation. 

My brother and I have possession of the land once owned by Granddad Archie. Talk about leaving an inheritance to your children’s children.

Robert, my great grandfather and Archie were good with their money in that they lived a modest lifestyle. Did not try to keep up with the Joneses and generally lived within their means.

The generations after the 1970s are ruled by greed and selfishness. The common use of credit cards is an example of this. 

The flashy advertising on TV taps into all of this by feeding into the narrative “You can have whatever you want and you can have it now.” 

It is the fear of missing out which the loan sharks are tapping into.

I have heard some bad money attitudes from people over the years and the most common is “You cannot take it all with you.”

This may be so but then why do these people go to work to earn money? People who spend all of the discretionary money with no thought for the future have no vision.

At some point in the future people will need money for medical expenses, dental expenses, new cars, retirement, and so on. The person with vision will set up their finances in such a way that they will have this money ready when the time comes.

“Men who have lots of money are selfish” is another one I have heard. If this is true then the men in our family who left large sums of money to their descendants must be selfish.

Only a gold digger would think like that and I will leave it at that.

“You have to spend your money on something.” is another comment I have heard. 

I am unaware of a law which says that you have to spend it. This kind of attitude will eventually lead to poverty at some point because there will come a time when your level of income will drop due to health or retirement. Making provision for your later years requires vision and maturity. It is the responsible thing to do.

Living within your means is a timeless principle. It was applicable to my great grandparents and it is still applicable today. The only difference is that in today’s society there is more pressure on people to part with their money and unless you learn to exercise self control and learn to discern then money will easily part ways with you. There is no magic formula, it is just a matter of applying the three basic rules of money management.

The three basics of personal finance are:

  1. Live within your means
  2. Save
  3. Invest

Once you have mastered the three rules then you will be better off than people who never look beyond the next pay day and just spend everything they make.

About this article

This article is of the opinion of the writer and is not financial advice. It may not be applicable to your personal circumstances, therefore discretion is advised. You may use this article as content for your website/blog or ebook.

Read my other articles on www.robertastewart.com

Get Rich Quick Gurus: Don’t be misle

Written by R. A. Stewart

”If it is too good to be true, it almost certainly is.”-anonymous

Have you ever seen those adverts on youtube from Get rich Gurus who claim to have made thousands of dollars per month and promise that you can by following their formula. Strange, that we never hear from those viewers who the videos are aimed at.

How do these people make their money?

The answer:

They have a call to action in the description of their video. Many of these call to actions are affiliate programs where the person behind the youtube channel gets a commission if you sign up with the website.

Having a degree of common sense and discernment will go a long way when you are confronted with people who are making these outrageous claims.

Here are some things to keep in mind:

1 You do not know what another person has done to get where they are nor do you know how much money they have outlayed to get where they are.

2 You do not know how hard another person has worked to get where they are. 

3 For everyone who has achieved something out of the ordinary there are thousands who tried the same thing and achieved nothing but a lighter bank account.

Re Flags to keep an eye out for.

They will use images of villas, stacks of cash and super cars to create what is known as “Fear of Missing out, FOMO”.

In the video they will make it seem so simple that anyone can do it by using the phrase “Simple step by step system.”

How do these people make their money?

Their income is made through the YouTube adsense program, from selling courses on how to make money, affiliate programs, and from promoting affiliate programs.

An aggressive call to action is a sure red flag. “Do this before its too late” is a phrase which is used to create a desire in the view to make an impulsive decision.

It pays to have a healthy level of skepticism when watching these videos. 

Turning to your own situation, ask yourself “How does this business fit in with my lifestyle?”

Ask yourself the following questions:

  1. How much time do I need to devote to this business and do I have the time to spend on this?”
  2. How much money is required to make this business idea work?
  3. “How will this affect my lifestyle?”
  4. Do I have the desire to persevere with this idea?

Don’t give up your day job!

One YouTube marketer puts this disclaimer on his videos, “Most people make nothing.”

That basically sums it all up. There is certainly nothing wrong with having a crack but being sensible about it will save you a pretty penny.

About this article

You may use this article as content for your blog or website. 

Read my other articles on www.robertastewart.com

The Value of a Rainy Day Fund

The Value of a Rainy Day Fund

Written by R. A. Stewart

Having a rainy day fund will enable you to pay for unexpected expenses when they arise. This could be for medical expenses, dental expenses, car breakdown, or anything else which may crop up from time to time.

A rainy day fund is not something you use to pay for discretionary spending items. Gym membership fees, a weekend away, or a day at the races are not things you would dip into your rainy day fund for.

When setting up this account you need to set guidelines as to what can come out of this account and what is a no no.

If you are in debt then should you have a rainy day account?

The answer to this is yes, but you MUST pay off your debt first before start depositing money into your rainy day account because the savings on interest will put you into a better financial position.

It is not sensible to have money in an account which pays next to no interest when you are paying high interest on loans.

If there is one bad habit which can be a hindrance to financial freedom it is the habit of borrowing money for stuff which should only be bought with discretionary spending money.

I hasten to point out that if you have debt of any kind then you do not have any discretionary spending money until that debt is paid off.

Getting into the habit of living more modestly means readjusting your lifestyle to fit in with your monetary goals. There are things which people spend their money on which are really choices. They have the choice to spend it on this and that or do without it. 

A bad money manager fritters away all of their discretionary spending money so that by the time the next payday comes around they are broke.

Having a raining day account will provide a cushion again unexpected events which can cause finance stress.

Where to keep it: Keep this money in a separate, easily accessible bank account — ideally a high-yield savings account. It shouldn’t be hard to reach when you need it, but keeping it isolated from your day-to-day checking account prevents you from accidentally spending it on regular expenses.

The benefits of a raining day account are:

  1. It protects you from high interest debt. If you have a $1,000 bill suddenly crops up then your only option may be to borrow that money at high interest rates.
  2. It gives you peace of mind. Knowing that you have money readily available to pay for some unexpected expense gives you some breathing space.
  3. It prevents you from selling investments at the wrong time. If you have investments in growth or balanced funds then you may be forced to sell them just when the markets are down. Having a rainy day account will insure that this does not happen.
  4. It buys you time and choices. If you suddenly suffer a job loss, a rainy day account will buy you time to decide on your next move instead of just making a random choice out of desperation.

About this article

This article is of the opinion of the writer and may not be applicable to your personal circumstances, therefore discretion is advised. This is not financial advice but the opinion of the writer.

Read my other articles on www.robertastewart.com

Escape the rat race on your own terms.

Financial insecurity shouldn’t hold you back from living fully. Discover practical tools, fresh mindsets, and actionable strategies to retire joyfully—without traditional wealth constraints.

📖 Download your copy of Retire Without Money now!

The Magic Power of Compounding


Written by R. A. Stewart

If you have any kind of financial knowledge you will know that the process of investing your money for years, sometimes decades and leaving your interest or dividends accumulate so that you end up earning interest off your interest is known as compounding.

Your investment starts to snowball once you have built up a decent portfolio. Using the process of compounding will enable you to achieve your goals faster.

Compounding also helps you to beat inflation which is a thorn in the side of those who are trying to get ahead in life. 

Investors who choose to have their interest or dividends paid into their bank account rather than have them added to their investment will find that their original investment will lose it’s purchasing power thanks to inflation. 

Your investing timeline is a big factor and the purpose of your investment.

If you are retired then you may prefer to have dividends paid into your bank account to help pay the bills and many do just that. The young ones usually let the income from their investments accumulate. This is common in retirement and mutual funds.

When you are saving for something then consider whether they are short-term, medium-term, or long-term goals. This matters because choosing the wrong type of investment for your timeline can affect how much you will end up with when it comes the time to cash in your investment.

For example it is not appropriate to invest your emergency fund in a growth fund due to it’s volatile nature because what is liable to happen is that just when you need the money the markets are down and there is less money available in your emergency fund than you thought there was.

At the other extreme, it is foolish to just leave your retirement fund in an ordinary savings account where you are paid minimal interest because inflation will erode the spending power of your money. 

Here is a break-down of the timelines of Short-term, medium-term, and long-term goals.

Short-term goals are within 12 months.

Medium-term goals are 1-5 years.

Long-term goals are over 5 years.

Getting into the habit of saving and investing will put you into a good position to withstand the financial shocks which life throws at you. This could be illness, job loss, family emergency, car breakdown, or anything else.

It takes vision to make some kind of provision for your future because you are preparing yourself for an event which may or may not happen. 

Then there are events which most people planned for such as buying a new car, further education,  saving for a house deposit, marriage, family, overseas trip, and retirement. People who have common-sense will make provision for events in their life which they expect to happen.

Investing your money for compound interest will help you to achieve your money goals sooner rather than having your interest or dividends paid to your bank account to spend. But it all depends on your personal circumstances.

About this article

This article is not financial advice and may not be applicable to your personal circumstances, therefore discretion is advised.

You may use this article as content for your blog/website or ebook.

Read my other articles on www.robertastewart.com


 Tired of seeing your bank charge you $5-10 every time you withdraw cash abroad PLUS that hidden foreign transaction fee? 🤯 That’s money that should be buying you a gelato, a beer, or a souvenir. Wise gets you the real mid-market exchange rate with only tiny, transparent conversion fees from 0.42%. Stop funding your bank’s next vacation. Fund yours. 

JOIN WISE HERE

Late Life Relationships: Financial Risks

Late life love: Things to consider

Written by R. A. Stewart

Getting involved with someone new late in life may sound like a good idea but there are financial considerations to consider not for yourself and your own family.

If you are receiving government support then you will be on the married rate whatever that is. It is your obligation to notice them of your new relationship status. Failure to do so may result in legal hassles later on.

Your will is something which needs to be changed when a new relationship starts. This will have serious implications for your children or whoever you intended to leave your assets to when you pass on. Your new spouse or partner will be entitled to everything irrespective of any promises made prior to entering into a new relationship.

There could be a situation whereby your family’s assets will be transferred to your spouse’s family should you pass on first.

Men in particular have to be wary of gold diggers and scammers.

There are people out there who prey on the emotions of others. Stories appear on the news occasionally of men who fell victim to romance scams.

As for gold diggers, some women are more interested in what’s in your wallet than what’s in your heart. Someone with discernment and common sense will know the motives of potential partners. 

There are some things which you need to consider when entering into a relationship late in life.

  1. Has this person got a good credit rating?

This may seem an unromantic question but if you are dating someone with a poor credit rating then you expose yourself to their debts. It could alter your estate planning as your spouse’s creditors could take a chunk off your estate.

  1. It can be difficult to change one’s existing lifestyle to accommodate someone else’s wants.
  2. Marriage may change your tax status, therefore it will pay to get advice on this.
  3. Marrying someone who has dependent children will make you equally responsible for child maintenance if your new spouse has children from a previous relationship.
  4. Estate planning needs to be carefully considered because the new relationship status will change who gets what if one person passes on. Clear communication with family members is essential. It is also important to get legal advice. This needs to be done prior to entering into a new relationship.
  5. Consider a prenuptial agreement in the event that the relationship turns sour.
  6. Placing your assets in a trust may be right for you if your desire is to leave your assets to your own family.

It is worth noting that as far as retirement savings go. Any contributions made to your kiwisaver during a relationship are considered matrimony assets, but only contributions made during the term of the relationship. The rules may be different in your own country regarding pensions. 

About this article

The contents in this article are of the opinion of the writer and may not be applicable to your personal circumstances, therefore discretion is advised. You may use this article as content for your website/blog or ebook.

Read my other articles on \www.robertastewart.com

Dividend Reinvestment Plan Explained 

Dividend Reinvestment Plan Explained 

Written by R. A. Stewart

A Dividend Reinvestment Plan, (often called DRIP or DRP) is an automated way to grow your portfolio by reinvesting dividends into the same company instead of receiving cash.

It is the same principle as investing for compounding interest.

Think of it as putting your money to work as soon as it is earned.

How a DRIP works

When a company you own shares in pays a dividend, you have two choices:

  1. Cash Payout: The money is paid into your brokerage or bank account.
  2. Reinvestment: The money is used to purchase additional shares (or fractional shares) in the same company.

Most major brokerages and many individual companies offer these plans. In many cases you can “opt-in” through your account settings and the account settings handles the rest.

How it Grows Your Wealth

When you opt into a Dividend Reinvestment plan you are not just owning more shares-its in the snowballing effect over time.

There are three key benefits.

  1. The Power of Compounding

Any dividends which are reinvested into the company will earn dividends during the next cycle which can accelerate your holdings in the long-term. An example is that you own 100 shares in a company. They pay a dividend and the dividend is converted into shares. You now own 102 shares.

  1. Dollar Cost Averaging

DRIPS purchase shares at regular intervals and this means:

(a) When the market is down you purchase more shares-its

(b) When the market is up you purchase fewer shares.

It all balances out in a year which mean that you are practising dollar-cost averaging.

  1. Reduced Fees and Discounts

There are reduced fees because you are purchasing more shares without the need for the normal transaction fees. 

It will pay to check on the conditions of the brokerage firm or the online platform where you have invested your money because not all of them are the same. 

Important considerations

DRIPS are a powerful tool for wealth-building, there are some things to consider.

Taxation: Dividends reinvested are still considered taxable income of the year that they are received even if you did not receive them in the form of cash.

Stock Imbalance: If a company pays a high DRIP then you could end up with a greater percentage of share in that company in your portfolio.

Income needs: If you may need the money for living expenses then taking your dividends in the form of extra shares may be impractical.

Summary

Feature Benefit to you

Automation “Invest and forget” helps to build discipline

Fractional Shares You own more shares even if it is a fraction of a share.

Compound Interest You accelerate your savings through compounding.

Why companies offer a DRIP

DRIPS are one way companies can generate more cash. Companies have a good idea of how much money they are likely to generate with DRIPS so it is a cost-effective way of raising capital. Reinvesting future dividends into the company means that an investor has confidence in the company’s prospects.

About this article

The contents of this article is based on the writer’s own opinion and experience and may not be applicable to your personal circumstances, therefore discretion is advised. You may use this article as content for your blog/website, or ebook.

Read my other articles on www.robertastewart.com

Fear of Loss will kill your chances of prosperity

Fear of Loss will hinder chances of prosperity

The fear of losing money will cause people to play it safe by not stepping outside their comfort-zone and not investing their money for greater returns. 

Leaving your money in an ordinary savings account will mean that inflation will erode the value of your money yet that is exactly what a lot of people do. They are afraid to take risks.

Some of this fear comes from those who had experienced the crash of 1987, better known as “Black Monday” when portfolios were hit hard. Some people lost their life-savings and more tragically, a lot of the money which went down the drain was borrowed money.

In these situations, shares were worth less than the money borrowed to purchase them.

There are risks which are worth taking and risks not worth taking. It takes discernment to tell the difference.

I remember once (about 2001) I bought shares in Air New Zealand and they almost went bust, well they would have if the government did not bail them out. The shares dropped to a low of fourteen cents a share. I bought my shares in the company at around $2 a share.

This was the last time I bought shares in an airline. It was an expensive lesson. 

I have known some people who never invest their money for fear of loss; they cannot handle the volatility of watching their balances go up and down yet they have no problem with buying their weekly lottery tickets. If they had deposited that same money into their kiwisaver then these people would have a fortune waiting for them once they reach the age of 65.

“You make your choices and your choices make you.”-Jim Addison, Scottish Pastor

It is all about choices.

The choices you make today will determine which choices you are able to make in the future.

If you have been sensible and joined a retirement scheme and contributed to it all of your life then this choice will give you more options in your later years.

Ask yourself these questions, “What action can I take today which my future self will thank me for?”

There will not be a single person who reaches the age of 65 or whatever the retirement age is in your country, who will regret ever joining  and contributing to a retirement fund.

It is everyone’s responsibility to get a financial education. This will help you to make right choices for your money. Apply what you have learned which are applicable to your personal circumstances.

Getting over your fear of loss will enable you to grow your wealth rather than just leaving it in the bank where inflation will steal the purchasing power of your money.

About this article

You may use this article as content for your blog, website, or ebook.

The contents of this article may not be applicable to your personal circumstances, therefore discretion is advised.

Read my other articles at www.robertastewart.com

What are you Saving For?

What are you Saving For?

Written by R. A. Stewart

The ASB television ad asks the question, “What are you saving for?”

When you know the answer to that question it becomes your goal. It leads to another question, “Where to invest your money until it is needed.”

In the TV ad, a boy was saving up to buy his favourite girl a gift. 

Developing the habit of saving for something specific from a young age is a good habit to get into. It teaches young people to be smart and strategic with their money.

As we get older, the things we are saving money for are in the hundreds, then thousands of dollars. As they say, “The difference between men and boys is the price of their toys.”

Choosing the appropriate kind of investment for your savings goal is important and the number one factor to consider is your timeline.

If you are saving for something long-term then just leaving your money in an ordinary savings account is not a smart way to save because inflation will erode the value of your money. 

Long-term is 5 years and more.

If you are saving for the medium term then you can be a little more conservative with your investing because you don’t want to invest in something volatile and find that there is a market meltdown just when you need that money.

Medium-term is between 1-5 years.

If you are saving for the short-term then you may need that money within the next twelve months then you can take a no-risk approach and just leave it in an ordinary savings account.

Short-term is up to 12 months.

Here are some long-term, medium-term, and short-term goals which you may be saving for.

Long-term

Retirement fund (Kiwisaver in New Zealand)

Education fund

Home deposit

Medium-term

Saving for a car

Overseas holiday

Marriage and kids

Short-term

Your emergency fund

Money set aside for rates, power, and other household utilities.

Once you have classified which category each fund belongs to it is then a matter of choosing the correct investment for each fund.

In managed funds there are three categories of investment, growth funds, balanced funds, and conservative funds.

Growth funds are suitable for long-term investments because they can be volatile but at the same time have the potential to grow your wealth. Young people have more time on their side to recover from market crashes, therefore, growth funds are appropriate for them, but that does not mean that retired people should not invest in growth funds as long as you are aware of the risks and that a market fall will not affect your lifestyle.

Balanced Funds are suitable for medium-term investing. They are not as volatile as growth funds but you are still exposed to the share-market which means your savings have the potential to grow but not at the same rate as growth funds.

Conservative Funds are less risky. You have a little exposure to the share market but not as much as with balanced and growth funds. Conservative Funds are more suited to short-term investing.

An ordinary savings account is appropriate for money set aside for rates and other house-hold expenses. Making the most of your discretionary spending money and using it for your savings goals can help you achieve them faster. A person who is poor with their money will fritter everything they have and then borrow for things they need.

It is important to avoid becoming fixated with your balances in whichever funds you have chosen. Balances will bounce up and down. That is the nature of the markets. 

There are plenty of opportunities to invest in this day and age with so many online investing platforms available in New Zealand. Sharesies, Hatch, and Kernel Wealth are three which I personally use. If you are from the US then Robinhood is a well-known one over there.

About this article

The views expressed may not be applicable to your personal circumstances, therefore discretion is advised.

You may use this article as content for your blog/website or ebook.

Read my other articles on www.robertastewart.com

Breaking into your Retirement Savings Early can be costly

Breaking into your Retirement Savings Early can be costly

Written by R. A. Stewart

New Zealand’s retirement scheme is called Kiwisaver. There is one thing which makes this scheme unique to retirement schemes of other countries and it is this:

There are circumstances when people can access their money prior to reaching their retirement age, 65 in New Zealand. People can access their money early for any of the following reasons:

  1. Terminal illness
  2. Going overseas permanently
  3. Purchasing their first home.
  4. Hardship.

Numbers 1 and 2 are quite understandable. Number 3 is that if you are purchasing your first home you may be able to use part of your kiwisaver for a house deposit.

Reason number 4 is the most common reason for premature kiwisaver withdrawals. In 2025 58,000 people withdrew money from their kiwisaver for hardship reasons. 

Breaking into your Kiwisaver early is not easy. You have to prove undue hardship, something which 58,000 people have managed to do. 

It is the fund manager’s supervisor who makes the decision to release your funds. They still have to follow a set of strict guidelines and a lot of people will have their application to withdraw early declined as a result.

Some people will see their Kiwisaver balance and think, “You can’t take it all with you, I can do a lot with that money,”

Kiwisaver is earmarked for your retirement or for your first home purchase and should not be touched otherwise you will be paying for it later on down the track.

The whole point of kiwisaver and any other retirement scheme is that you are saving money for your retirement and do not withdraw and keep contributing. 

Consistent long-term savings work well thanks to the magic of compound interest. 

Any break in savings will interfere with this process. 

With compound interest you earn interest on the interest and this helps your savings to grow faster. 

At retirement there can be a big pot of money waiting for you thanks to compound interest which is a friend of the long-term saver.

Making right choices

It is important to make the right choices when making important financial decisions, whether that is entering into a new relationship, purchasing a car, taking out a loan, or making major home improvements. The pros and cons need to be explored thoroughly and not to be rushed into.

All of these major decisions will have consequences, which will eventually lead to an outcome. 

One big mistake is to make major decisions based on today’s circumstances as if today’s circumstances will remain the same forever. Investing some if not all of your discretionary spending money in a share market fund other than kiwisaver will improve your financial know-how. There are several online share-market investing platforms available to begin your investing portfolio if you have not already started one. It is just a matter of being consistent with your investing and letting compounding interest do its work. 

About this article

The contents of this article is of the experience and opinion of the writer and may not be applicable to your personal circumstances, therefore, discretion is advised. You may use this article as content for your blog/website or ebook.

Read my other articles on www.robertastewart.com